Volume #18 | IssueNo. 328/2026 | September 2026
Creating Change, One Connection at a Time
As professionals, how can we become contributors to the Theory of Change framework in the context of community impact? The question matters because it helps us find deeper meaning in our work. When we understand how our role contributes to a larger social outcome, our efforts become more than professional responsibilities. They become part of a broader purpose shared by the organizations and communities we serve.
For a Company Secretary (CS), the connection is particularly relevant. Under the Companies Act, 2013, Corporate Social Responsibility (CSR) is an integral part of corporate governance. A CS plays a critical role in planning, implementing, monitoring, and ensuring compliance of CSR initiatives, while acting as a bridge between the Board, the CSR Committee, management, and stakeholders.
In my professional role, I do this routinely. However, over the years, I have realized that a Company Secretary can create value far beyond advisory and compliance services.
A significant challenge in the CSR ecosystem is helping the right donor find the right implementing partner.
Corporates often struggle to identify NGOs that can utilize CSR funds effectively and responsibly. Questions naturally arise:
- Is the NGO credible?
- Can it implement the project within the agreed timeline?
- Does it have the governance structures required for accountability?
- Is it compliant with the applicable CSR regulations?
- Can it demonstrate transparency in the utilization of funds?
On the other hand, NGOs face an equally challenging search for aligned donors. Their concerns are often different but equally important:
- Does the corporate’s CSR agenda align with our mission?
- What is the available CSR budget?
- Is the organization looking for a one-time contribution or a long-term partnership?
- What level of due diligence will be required?
- How long will approvals take and when will funds be released?
- Will the implementation timeline allow adequate time for project execution?
This, in my view, presents a golden opportunity for Company Secretaries.
We can become more than governance professionals. We can become matchmakers, trust-builders, and catalysts of impact.
We can help donors and implementing agencies discover each other. We can support due diligence, establish credibility, facilitate expectation-setting, and help ensure that commitments made by both sides are fulfilled. As someone wisely said: “Giving becomes meaningful when it builds not dependence, but trust between the giver and the receiver.”
Recently, I experienced this firsthand when I was invited to inaugurate a beautiful school building constructed by the https://www.vonishafoundation.org/, an organization I have had the privilege of serving as a professional advisor and mentor since its inception.
Walking through the campus was a deeply fulfilling experience. Several classrooms bore the names of corporate donors, and I was delighted to find that many of those companies were organizations with which I am professionally associated and had recommended supporting the Foundation through CSR contributions.
What was even more gratifying was seeing how those relationships had evolved over time. These companies had not merely donated funds. They continued to support subsequent projects and actively encouraged employee volunteering initiatives. At the same time, the NGO had utilized the CSR funds efficiently, constructing spacious, well-ventilated classrooms within a remarkably short period and appropriately recognizing the contribution of every donor.
It was a perfect example of:
Promise Made. Outcome Delivered.
The impact was visible everywhere.
Children streamed eagerly into their new classrooms, settled onto gleaming benches, and looked attentively at freshly installed teaching boards. The infrastructure was tangible, but so was the transformation. In that moment, I witnessed how a simple act of connecting the right donor with the right organization could create lasting value.
The experience filled me with immense gratitude and a profound sense of fulfillment. Kathy Calvin once said: “Giving is not just about making a donation. It is about making a difference.”
I would like to add:
The difference is felt not only by the receiver and the giver, but also by the facilitator who helps build trust between them.
Perhaps that facilitator could be you.
On 17 September, the Government of India also chose to make a difference. The highlight of this 328th issue of Samhita is undoubtedly the EPF wage revision announcement, which generated significant discussion across the corporate sector and prompted a series of clarifications from the PF authorities.
Read our cover story for a detailed analysis of the development, along with other key regulatory updates and insights from September 2026.
For access to previous issues of Samhita and readers’ feedback, please visit:
👉 http://www.sharadasc.com/resource-center/
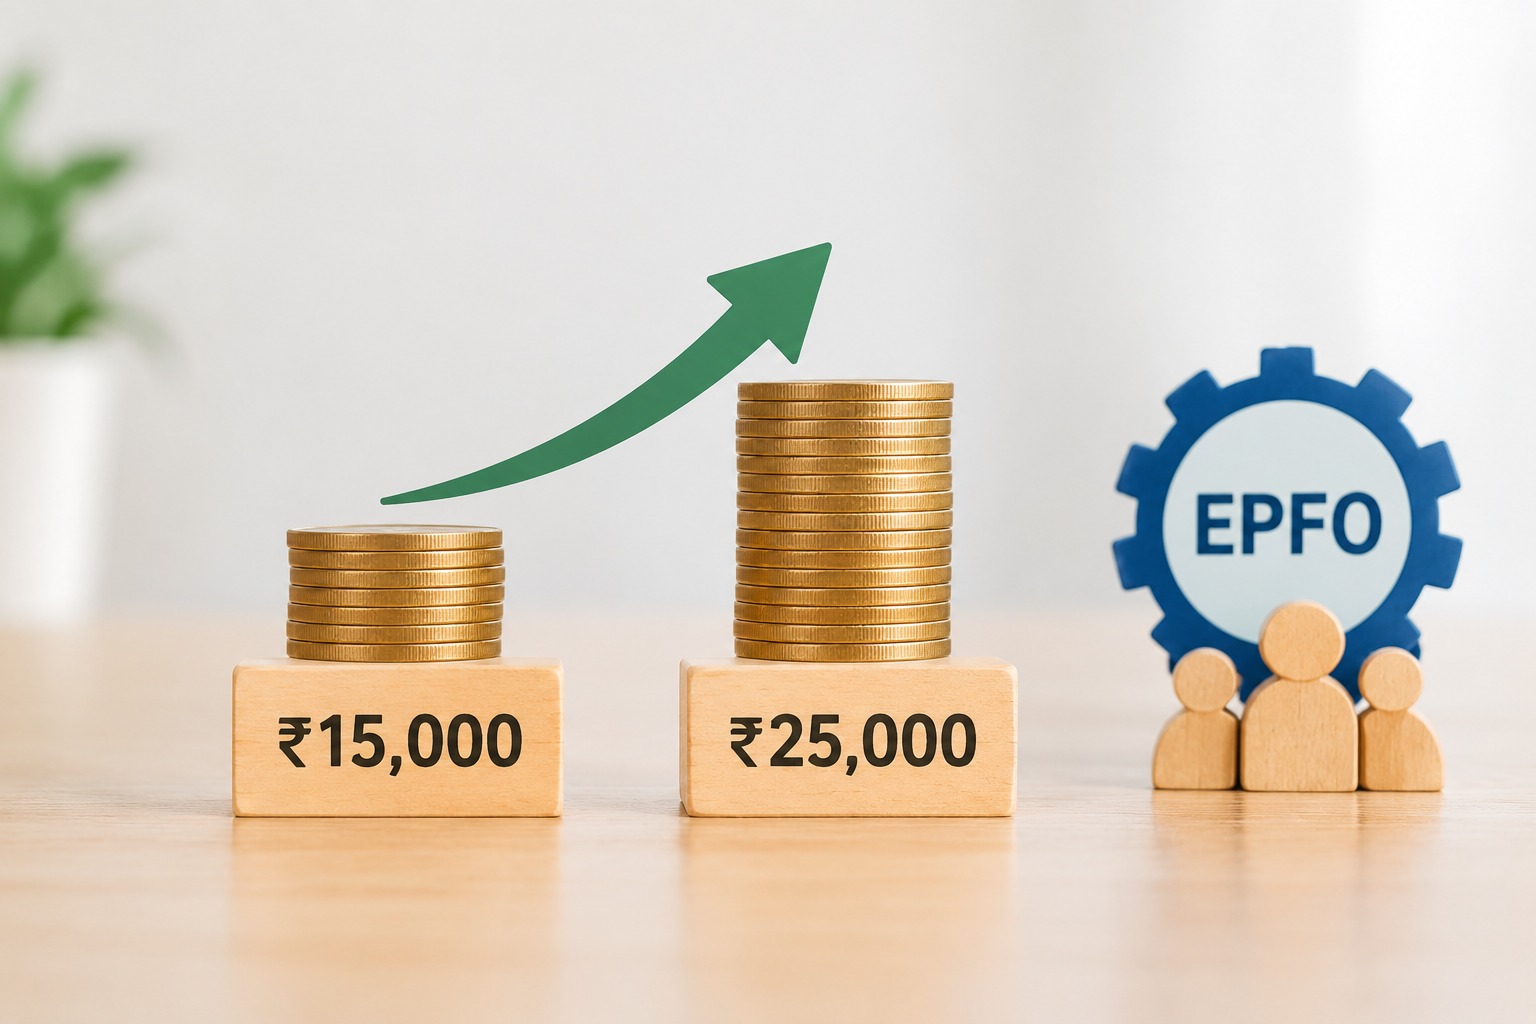
EPFO Wage Ceiling Increased from Rs.15,000 to Rs.25,000

The Government has enhanced the wage ceiling for mandatory EPFO coverage from Rs.15,000 to Rs.25,000 per month, effective September 17, 2026. The ceiling, which was last revised in September 2014, has been increased to align the social security framework with rising wages, incomes and the expansion of formal employment. The revision is expected to bring more than 51 lakh additional employees within mandatory EPFO coverage, extending access to EPF, EPS and EDLI benefits.
The mid-month implementation of the revised ceiling, however, created significant operational challenges for employers and payroll teams, particularly for processing September 2026 contributions. Since the revision took effect from 17 September, contributions for September have to account for the two periods—up to 16 September under the Rs.15,000 ceiling and from 17 September under the revised Rs.25,000 ceiling. To address the resulting implementation issues, EPFO has issued detailed FAQs clarifying matters such as pro-rata contribution calculation, filing of a single ECR for September, recovery of additional employee contributions through the October payroll in specified cases, CTC arrangements and treatment of existing members.
FAQs on the revision of the EPFO Statutory Wage Ceiling may be referred to below.
(Open FAQs on revision of EPFO Statutory Wage Ceiling)
(Open Notification dated September 17, 2026)
RBI Update
The Reserve Bank of India has issued the Foreign Exchange Management (Export and Import of Goods and Services) (Amendment) Regulations, 2026, effective October 1, 2026, introducing the following key changes to the principal regulations:
Particulars | Regulation No. | Foreign Exchange Management (Export and Import of Goods and Services) Regulations, 2026 | Amendment w.e.f. 1 Oct 2026 |
Realisation & repatriation of export proceeds | Regulation 5 | 15 months from the date of export | 9 months from the date of export |
The period for realisation and repatriation of full export value where it is invoiced/ settled in Indian Rupees | 1st Proviso to Regulation 5 | 18 months from the date of shipment | 12 months from the date of shipment |
Exporters in Caution List | Insertion of Proviso after regulation 13 | — | Exporters placed on the Caution List as on September 30, 2026 will continue to be governed under the Regulation 16 of the Foreign Exchange Management (Export of Goods & Services) Regulations, 2015 until removed from the list |
Powers of Authorised Dealers (ADs) | Regulation 20 | Certain transactions undertaken before October 1, 2026 required RBI approval under the erstwhile 2015 Regulations/Master Directions – Foreign Exchange Management (Export of Goods and Services) Regulations, 2015, Master Direction – Export of Goods and Services (FED Master Direction No. 16/2015-16, dated, January 01, 2016 as updated till July 17, 2026), and Master Direction – Import of Goods and Services (FED Master Direction No. 17/2016-17, dated, January 01, 2016 as updated till January 12, 2026). | ADs are empowered to handle such pending transactions, including export/import of goods and services and merchanting trade, without requiring the erstwhile RBI approval |
The amendment reduces the prescribed period for realisation and repatriation of export proceeds from 15 months to 9 months, while also providing transitional protection for existing Caution List exporters and enabling Authorised Dealers to handle certain legacy transactions that previously required RBI approval.
DGFT Updates
DGFT, through Trade Notice No. 24/2026-27 dated August 31, 2026, has introduced automated issuance of Free Sale and Commerce Certificates (FSC) for items not covered under the Drugs & Cosmetics Act, 1940 under the existing provisions of the Handbook of Procedures. The initiative replaces the earlier process, where applications were routed to Regional Authorities for manual examination, verification and approval, with a rule-based, system-driven workflow.
Under the new mechanism, applications meeting predefined parameters will be processed and issued automatically, while cases requiring specific verification or not meeting the prescribed conditions will continue to be referred to the concerned Regional Authority. The system also incorporates risk-based monitoring, allowing certain automatically approved applications to be subsequently flagged for review. The initiative is expected to reduce manual intervention, improve turnaround times and support paperless trade facilitation.
DGFT has launched an Open API facility for issuing Certificates of Origin (CoOs) via the Trade Connect e-Platform. Formally introduced on September 7, 2026, this digital initiative allows eligible exporters to integrate their internal Enterprise Resource Planning (ERP) or accounting software directly with DGFT’s electronic system. The primary goal is to foster ease of doing business by cutting down manual data entry, boosting data accuracy, and enabling seamless, automated electronic data exchanges for both Preferential and Non-Preferential CoOs.
To access this facility, organizations must complete their onboarding registration on the designated portal, whitelist their public IP addresses, and configure a compliant document signer for payload encryption. The secure framework enforces strict data integrity and non-repudiation. The multi-step API process flow enables automated transaction ledger tracking. The exporters can reach out to the DGFT Helpdesk through toll-free assist lines or email for onboarding support.
The Government of India has ordered the creation of a Central Processing Department (CPD) within the DGFT to implement its nationwide Faceless Trade Facilitation System. Formally issued on September 14, 2026, the memorandum outlines a centralized approach to handle trade-related applications without jurisdictional barriers, designed to optimize processing efficiency, minimize human interface, and elevate transaction transparency. The physical infrastructure for this central processing unit is set up at the Centralised Laboratory (CLA) Delhi branch, drawing on specialized staff from both DGFT Headquarters and surrounding Regional Authorities.
To ensure senior oversight and complete readiness before the system is officially dedicated to the nation during the second fortnight of October 2026, five top-ranking officials at the level of Additional Director General of Foreign Trade have been given additional charge of CPD Delhi. They are tasked with executing workflow assignments across various processing streams, strictly monitoring application turnaround times, providing rigorous quality assurance on trade decisions, and maintaining system readiness.
The DGFT, vide Notification dated September 15, 2026, has amended the Foreign Trade Policy, 2023 to provide a de minimis exemption from the requirement of Registration-cum-Membership Certificate (RCMC) or Certificate of Registration for export consignments having an FOB value not exceeding Rs. 3,00,000.
The exemption is intended to facilitate small-value exports, particularly through postal, courier and other emerging export channels. Export consignments exceeding Rs. 3,00,000 will continue to require a valid RCMC or Certificate of Registration wherever otherwise applicable under the FTP. The amendment is effective immediately from the date of notification.
SEBI Update
SEBI through its circular issued on September 7, 2026 has granted Angel Funds additional time to comply with the Accredited Investor mandate. Under the earlier framework notified on September 9, 2025, Angel Funds registered after September 10, 2025 were required to onboard only Accredited Investors, while those registered on or before September 10, 2025 had a transition period until September 8, 2026. During this period, they could admit up to 200 non‑Accredited Investors, but no fresh contributions from such investors were allowed thereafter.
Based on the representation from the Alternative Investment Fund (AIF) Industry requesting additional time for the then existing Angel Funds to meet the Accredited Investor mandate, SEBI has extended the deadline to March 31, 2027 for Angel Funds registered on or before September 10, 2025. These funds may continue to onboard up to 200 non‑Accredited Investors until the new cut‑off date, but contributions from non‑Accredited Investors will not be permitted beyond March 31, 2027.
IBBI Update
The IBBI, vide its notification dated September 22, 2026, has substituted Regulations 31(3) and 31(4) of the Insolvency and Bankruptcy Board of India (Liquidation Process) Regulations, 2016, which govern the preparation of the list of stakeholders by the liquidator and the related compliance requirements, with a revised Regulation 31(3).
Under the revised Regulation 31(3), a liquidator may modify an entry in the list of stakeholders upon receipt of additional information warranting such modification. Further, the liquidator is required to intimate the Adjudicating Authority of any such modification within thirty days from the date on which the modification is made.
Open IBBI (Liquidation Process) (Fifth Amendment) Regulations, 2026 dated September 22, 2026)
Labour Law
The Ministry announced an Amnesty provision under the EPF Scheme, 2026 for PF Trusts that are recognised under the Income Tax Act but do not have a formal exemption order under the EPF legislation.
The one-time opportunity permits eligible PF Trusts to seek retrospective regularisation of their exempt status. The Amnesty is available for six months from the notification of the EPF Scheme, 2026, i.e. until December 28, 2026.
Importantly, certain requirements applicable under the Code on Social Security, 2020 — including minimum employee headcount, corpus size and the three-year compliance requirement — are waived for this regularisation process.
Companies operating recognised PF Trusts should verify whether their Trust has a valid statutory exemption order and, where absent, assess eligibility under the Amnesty provisions.
The Government has introduced VISHWAS, 2026, a one-time settlement scheme enabling eligible establishments to settle certain long-pending disputes relating to EPF damages for delayed contribution payments at substantially reduced rates.
Under the scheme, the damages are reduced to:
- Delay up to 2 months – 0.25% per month
- Delay of 2–4 months – 0.50% per month
- Delay beyond 4 months – 1% per month
The scheme covers specified cases relating to delays prior to 14 June 2024, including matters pending before courts/tribunals, penalty orders where recovery is pending, and certain cases where proceedings have not yet culminated in a final order. The scheme is available until 28 December 2026.
ESG Updates
Union Minister of State for Environment, Forest and Climate Change, Shri Kirti Vardhan Singh, launched India’s Net Zero Portal and the National Action Plan on Climate Change (NAPCC) Dashboard in Mumbai on World Ozone Day 2026. The Net Zero Portal provides a centralized platform for Indian entities to voluntarily register and disclose their Net Zero commitments, including GHG emissions, targets, annual progress and pathways involving clean energy, energy efficiency, technology and carbon removals. It aims to enhance transparency and encourage credible, long-term climate planning, with successful declarations receiving acknowledgement from the Ministry of Environment, Forest and Climate Change.
The NAPCC Dashboard offers a consolidated digital view of progress across India’s National Missions on Climate Change, enabling systematic monitoring, stronger inter-ministerial coordination and evidence-based assessment of climate action. Together, the two platforms are intended to improve transparency, identify implementation gaps, consolidate climate-related information and strengthen the alignment between India’s domestic climate initiatives and its international commitments. The initiatives underline the government’s focus on technology-enabled governance and wider participation in India’s transition towards a low-carbon and climate-resilient future.
The global corporate sustainability agenda is increasingly shifting toward Asia-Pacific, China and the European Union, according to the State of Sustainable Business 2026 report by GlobeScan and BSR. Around 62% of surveyed sustainability professionals expect Asia-Pacific’s influence to increase over the next three years, driven by its role in clean-technology manufacturing, renewable energy, batteries and global supply chains. China’s strength in clean-energy technologies and the EU’s regulatory influence are expected to remain significant, while the US may see a relative decline in influence.
The report also highlights a broader shift in how companies approach sustainability. Regulation has become a major driver, with 76% of respondents identifying it as a key influence, compared with 31% in 2016. At the same time, sustainability budgets remain constrained, many companies are reassessing their targets, and there is a growing gap between sustainability teams and senior management on the strategic importance of ESG. Climate adaptation and AI-related environmental and social impacts also remain areas where corporate preparedness is limited. Overall, sustainability is becoming more focused on compliance, risk management, supply-chain resilience and practical implementation, rather than broad public commitments.
Tax Updates
The Income-tax Rules, 2026 have been amended to introduce enhanced reporting requirements for TDS on consideration paid by a resident individual or HUF for transfer of immovable property under Section 393(2).
A new Schedule E has been introduced, along with revisions to Forms 132 and 141, to capture additional details relating to the buyer, seller, property, tax residency, payment and tax deducted. The amendments will be effective from October 1, 2026, requiring buyers to furnish the additional particulars from that date.
The CBDT has extended the due date for furnishing tax audit reports for AY 2026-27 from September 30, 2026 to October 21, 2026. Consequently, the due date for filing income-tax returns for assessees covered by the specified audit provisions has been extended from October 31, 2026 to November 21, 2026.
The extension provides an additional 21 days for taxpayers and tax professionals to complete audit-related documentation and return filing. The extension was announced by the CBDT through a press release.
GST Update
The GST Portal has been updated to enable taxpayers to file electronic appeals in Form GST APL-01 even where the demand order reflects a NIL or zero outstanding demand.
The change addresses situations where taxpayers may have paid the disputed tax amount before issuance of the final order, resulting in a zero balance in the demand order and previously preventing them from filing an online appeal. The portal now allows such taxpayers to pursue an appeal against the underlying demand order despite the NIL demand reflected on the portal.
Quote of the day
“We rise by lifting others.” - Robert Ingersoll
Disclaimer: The contents of this Newsletter are only a summary and has not dealt with any issue in detail. Any action taken or proposed to be taken must be in consultation with professionals and not merely based on the articles / news updates. S. C. Sharada & Associates disclaims all liability on action taken without professional advice.